A mortgage pre-approval is useful, but it does not automatically mean a buyer’s documents have been checked or an underwriter has reviewed the file. For agents, the important question is not simply, “Does the buyer have a letter?” It is, “What has the lender verified, what remains open, and what could still change?”
That distinction matters in today’s market. Freddie Mac reported that the 30-year fixed mortgage averaged 7.40% for the week ending October 8, 2026, up from 7.28% the week before. At a higher rate, a change in qualifying income, assets, or debt can have a more immediate effect on a buyer’s payment and loan options.
Use the quick scorer below to start a more specific conversation with a lender. It is a discussion aid, not a credit decision or loan approval.
Verification Ladder Scorer
Check what the lender confirms is complete. The result is a conversation starter, not a lending decision.
- Credit pulled
- Income verified
- Employment verified
- Assets verified
- Gift funds documented, if applicable
- File reviewed by underwriting
- Underwriting conditions issued
- Intended property type discussed
What Changed
The verification process is a ladder, not a set of interchangeable labels. Lenders may use these terms differently, so ask what work is actually complete rather than relying on the name of the stage.
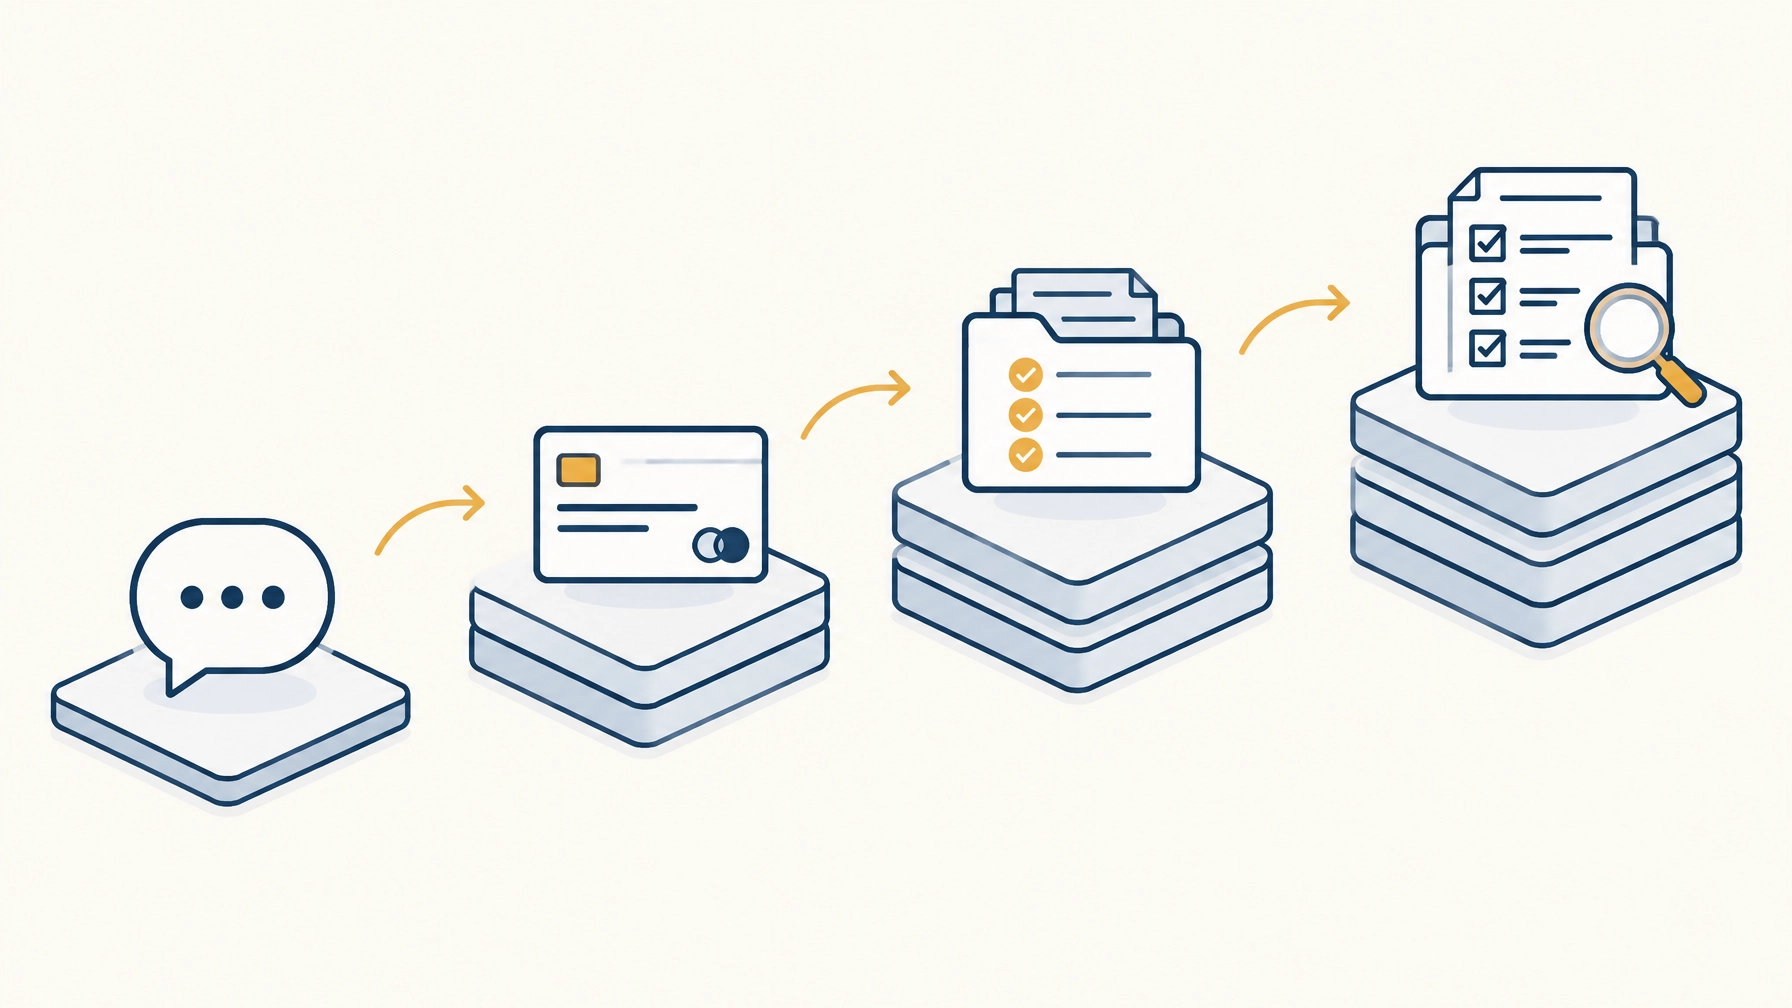
| Stage | What is generally checked | What may remain open |
|---|---|---|
| 1. Pre-qualification | Borrower-stated information. Typically no document verification. | Credit, income, assets, employment, and underwriting review. |
| 2. Standard pre-approval | Application and credit review; an initial look at capacity. | Income and assets may be unverified; the file may not have been underwritten. |
| 3. Verified pre-approval | Income, employment, and assets documented; file prepared for underwriting. | Underwriter review, conditions, and property-specific questions. |
| 4. Pre-underwriting | Borrower documents reviewed by underwriting; conditions issued. An automated underwriting finding may also be attached. | Property, appraisal, title, insurance, project eligibility, and remaining borrower conditions. |
Why It Matters
The gap between “a lender looked at the application” and “an underwriter reviewed the supporting documents” can become visible after an offer is accepted. If a pay structure, asset source, or debt is different from what the initial application showed, the lender may need more documents or may need to revisit the qualifying numbers.
That risk matters in a market where affordability is sensitive to financing details. Freddie Mac’s Primary Mortgage Market Survey placed the 30-year fixed average at 7.40% on October 8, 2026. Meanwhile, the National Association of REALTORS® REALTORS® Confidence Index reported that about 12% of contracts had delayed settlements and roughly 6% were terminated in the July 2026 reporting period. Financing and appraisal issues can contribute to delays and cancellations.
Negotiating conditions have also become relevant. Redfin’s August 2026 analysis estimated that sellers outnumbered buyers nationally by 57.9%. Its August concession analysis found seller concessions in 44.7% of sales. These figures do not mean every seller will negotiate, but where sellers have options, confidence in the buyer’s financing may help an offer stand out.
The Mortgage Bankers Association’s weekly survey also reported purchase applications down 15% year over year for the week ending October 2, 2026. The buyers still making offers may be highly motivated, but sellers and their agents still need to evaluate whether the financing plan is well prepared.
A pre-underwritten file can support a buyer’s request to narrow a financing contingency, or consider waiving it, with more information about the borrower’s readiness. That choice belongs to the buyer and should be made only after discussing contract risks with the appropriate professionals. Underwriting does not remove property risks or guarantee a closing.
Example Scenario
Illustrative scenario: Kayla, an agent in the Nashville area
Kayla is presenting two offers at the same price. The first includes a one-page pre-approval letter, but the lender has not verified income and has not provided an outstanding-conditions summary. The second buyer’s file has been reviewed by underwriting. The lender identifies two remaining property-level items and is available to answer questions.
Before submitting, Kayla calls both lenders and asks: “Have income, employment, and assets been verified? Has an underwriter reviewed the documents, or is there only an AUS result? What conditions remain, and what must be resolved for this property type?”
The first lender confirms the letter reflects an initial credit-and-capacity review. The second confirms the underwriter reviewed the borrower documents and that the remaining items relate to the property, while emphasizing that appraisal, title, insurance, and final borrower checks are still required.
Kayla gives the seller’s agent a concise, factual comparison: the offers have the same price, but one buyer’s documents have not yet been underwritten while the other has had a borrower review, with property conditions still open. She documents the lender responses and the seller’s decision through the normal offer process. The stronger preparation informs the decision; it does not guarantee which offer the seller will choose or that either loan will close.

Tips
Use these questions and habits to place a buyer’s file on the verification ladder before you present the offer:
-
Call the lender before you present, not after.
Confirm the lender knows the buyer is making an offer and can discuss the file within privacy and authorization requirements.
-
Ask for the stage using specific language.
“Is this a credit-and-capacity review, a verified pre-approval, or a completed underwriting review?”
-
Confirm how income and employment were verified.
Ask whether the lender reviewed current income documents and has a plan for confirming employment again before closing.
-
Ask whether assets and gift funds were documented.
Find out whether the funds needed for down payment, closing costs, and reserves are visible and sourced as required.
-
Get the outstanding-conditions list in writing.
Separate borrower conditions from property or closing conditions, and ask which are already satisfied.
-
Confirm the property type the review covers.
A single-family home, condominium, manufactured home, or other property type may raise different eligibility questions. Ask whether the specific type in the offer has been considered.
-
Distinguish an AUS result from underwriter review.
An automated “approve/eligible” finding can be helpful, but by itself it does not mean an underwriter reviewed every supporting document.
-
Ask what could change the file.
New debt, a job or pay change, large deposits, changes in down payment funds, and a material change to the transaction may require a fresh look.
-
Start document gathering before the buyer is under contract.
Encourage timely, secure document delivery to the lender rather than waiting for a deadline.
-
Do not assume the loan officer and underwriter agree because a letter is signed.
Ask who reviewed the file and whether unresolved questions have been referred to underwriting.
If you need help organizing that conversation for a particular buyer’s timeline, Talk to the Expert. Keep the discussion focused on what is verified and what remains, rather than asking for a promise of approval.
Bottom Line
Pre-approval is a preliminary view of credit and capacity. Pre-underwriting means borrower documents have been reviewed by underwriting and conditions have been issued. That is a meaningful difference, but neither tier eliminates property-specific checks or the need to keep the buyer’s finances stable through closing.
Before you present an offer, ask what was verified, who reviewed it, which conditions remain, and what could change the file. Clear answers help you set expectations, communicate the buyer’s readiness accurately, and help the seller compare offers on more than price alone. Buyers preparing to make a move can Get Mortgage Ready by organizing their documents and discussing the process with a qualified mortgage professional.
